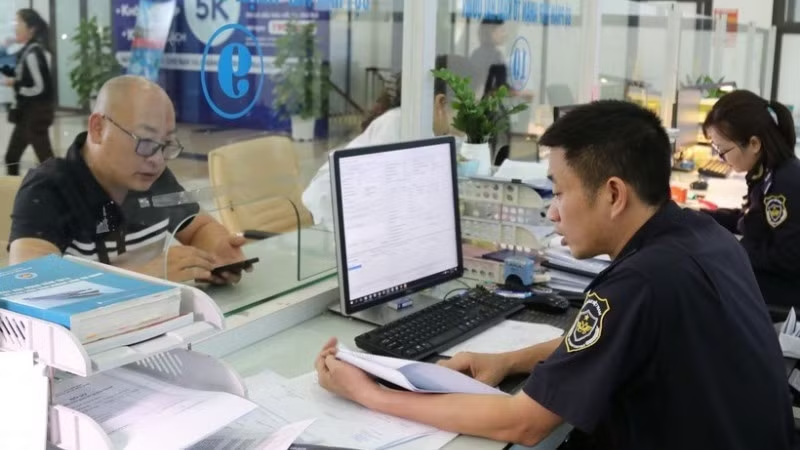
For import and export businesses, a single tax payment involves multiple stages: preparing payment documents, debiting and transferring funds, transmitting information, reconciliation, and accounting. Data at each stage must be consistent so that customs authorities have a basis for recording payments made and confirming the fulfilment of tax obligations in accordance with regulations. Therefore, the quality of information processing after payment is an important part of the procedural process.
The Ministry of Finance is seeking comments on a draft circular stipulating procedures for the collection and payment of taxes, other revenues, late payment interest, and penalties in respect of exported, imported, and transited goods, as well as means of transport entering, exiting, or transiting the country. The draft sets out specific provisions on payments into the state budget, tax guarantees, information exchange, verification, and the handling of errors arising during implementation. It is expected to replace Circular No. 184/2015/TT-BTC and Circular No. 51/2025/TT-BTC.
Seamless connectivity from payment to accounting
At a recent forum titled “The Tax and Customs Sectors Accompany Businesses to Promote Double-Digit Economic Growth”, Tran Duc Hung, Deputy Director General of the Customs Department, highlighted the need to ensure consistency between legislation, professional procedures, and technological systems, while strengthening connectivity, data sharing, and automation.
Regarding procedures for the collection and payment of import and export taxes, the draft circular currently under consultation by the Ministry of Finance specifies the information required for exchange and reconciliation between systems. Accordingly, once the customs authorities have provided an identifier for the amount payable, the tax payment document must include this code. The reference number is automatically generated by the payment system in which the document is created, ensuring uniqueness for each unit and remaining unchanged throughout the transmission and receipt process.
This information serves to identify amounts payable and facilitate data exchange between the parties. The draft also stipulates that a single payment schedule or payment order may be used to pay taxes for one or more customs declarations; fee payments may be made for one or more consignment dossiers.
Through the Customs Electronic Payment Portal, taxpayers can look up amounts payable, select the amounts to be paid into the state budget, and use the system to prepare payment orders. After checking the information, taxpayers select the unit from which the funds will be debited and digitally sign the payment request. If taxes must be paid into different collection accounts, separate payment orders must be prepared for each account.
The procedure also provides for cases in which information on an amount payable is not yet available on the Customs Electronic Payment Portal. In such cases, taxpayers must enter all the required information in the payment document, select the unit responsible for processing the transaction, and digitally sign the request to debit funds for payment into the state budget.
After debiting the funds, organisations participating in the payment process are responsible for immediately transmitting revenue information to the Customs Electronic Payment Portal. For transactions made through the portal, the system automatically reconciles the information received against the information entered by the taxpayer. Where the data match, the centralised tax accounting system automatically records the settlement of outstanding tax liabilities, confirms the fulfilment of tax obligations, and calculates late payment interest, if applicable, in accordance with regulations.
If the transmitted information contains errors, the Customs Electronic Payment Portal issues an error code and rejects the update. Once the relevant unit has made the necessary corrections, the system records the transaction and confirms the fulfilment of tax obligations in accordance with regulations. Thus, the requirement for timely information transmission goes hand in hand with accuracy checks before data is updated.
At the same forum, Dau Anh Tuan, Deputy Secretary-General and Head of the Legal Department of the Viet Nam Chamber of Commerce and Industry (VCCI), acknowledged the benefits brought by the digitalisation of administrative procedures. However, according to feedback from the business community that he cited, difficulties were more concentrated in tax refunds, implementation guidance, and consistency in the application of the law.
These observations on policy implementation highlight the need to further improve the way administrative matters are handled in the electronic environment. For import and export tax payments, alongside payment channels, the draft circular contains specific provisions on verification, the adjustment of payment documents, and coordination among relevant units in handling information.
Defining responsibilities at every stage
At the 7th scientific conference on “Tax, Customs, and Logistics Policies and Management” in 2026, held by the Faculty of Taxation and Customs at the Academy of Finance in Ha Noi on October 17, Nguyen Van Phung, former Director General of the Large Enterprise Department under the General Department of Taxation, recommended the establishment of a consistent implementation mechanism, clearly defining the responsibilities of each agency, linking them to performance evaluation indicators, and ensuring coherence among documents guiding the implementation of laws.
Regarding the handling of errors in the collection and payment of import and export taxes, the draft circular currently under consultation by the Ministry of Finance specifies the responsibilities of each party. Accordingly, the unit at which an error arises must take responsibility for it, proactively identify its cause, remedy the consequences, and send electronic verification requests to relevant units for coordinated resolution.
When an error is detected in the information declared on a document for payment into the state budget, the taxpayer must prepare an adjustment request and submit it to the customs authorities. The application to amend the payment document must be prepared online, digitally signed, and submitted through the electronic portal in accordance with the draft regulations.
Article 19 stipulates that, within one working day of receiving an electronic verification request, the customs authorities must send a notification regarding the resolution of the taxpayer's application. During the processing of the application, if information requiring clarification or additional supporting documents is needed, the customs authorities must issue a request for supplementation. Explanations and supporting documents are to be received electronically.
The one-working-day deadline applies to the issuance of the notification regarding the resolution of the application. The process may also, where necessary, involve the provision of additional information and coordination with the State Treasury to make adjustments. The customs authorities check the information and prepare a request to adjust state budget revenue, which is sent to the State Treasury as the basis for making the accounting adjustment. They then send the outcome of the application. If no adjustment is made, the notification must clearly state which state budget revenue information will not be adjusted.
For amounts transferred in excess of the taxpayer's payment request, the draft stipulates verification responsibilities shared by payment organisations, customs authorities, and the State Treasury. The handling of excess transfers and refund requests must ensure that customs declarations for which debts have already been offset, tax obligations have been confirmed as fulfilled, and goods have been cleared through customs or released are not affected.
When a system failure occurs, the relevant parties are responsible for identifying its cause. Within one working hour, they must notify one another internally and inform taxpayers so that the issue can be addressed. Based on the state budget payment documents provided by the taxpayer, together with information from banks, payment organisations, and the State Treasury, the customs authority responsible for administering the revenue item decides whether to confirm the fulfilment of tax obligations. Once the transmission failure has been resolved, the revenue information is retransmitted so that the customs authorities can record the offsetting of outstanding tax liabilities.
For electronic tax guarantees, the customs system checks the information transmitted by banks participating in tax collection against the information declared by taxpayers on their customs declarations. Where the information matches, the system automatically confirms the fulfilment of tax obligations through the use of a guarantee. If the information does not match, the system withholds confirmation and provides the reason.
If the information in the guarantee letter provided to the taxpayer differs from that transmitted to the customs authorities, the bank is responsible for supplying accurate information again so that the taxpayer can make the correct declaration. If an error is found in the contents of an issued guarantee letter, the bank must send a cancellation message and issue a new guarantee letter to replace it. The replacement letter must contain all the information required by regulations, remain valid for at least the entire validity period of the letter requested to be cancelled, and cover an amount equal to or greater than the tax amount already guaranteed.
Improving tax collection and payment procedures therefore requires an end-to-end approach, from the preparation of payment documents to the recording of funds, covering both routine transactions and the handling of errors and incidents. For the draft that is currently open for consultation ahead of October 22, 2026, the provisions on coordination and responsibility for handling issues warrant careful consideration to ensure that they can be implemented effectively.