To ensure resources reach the right businesses at the right time, lending assessments need to be renewed, cash flow data better utilised, and risk-sharing mechanisms improved, alongside efforts to strengthen businesses' management capacity.
Capital must arrive at the right time
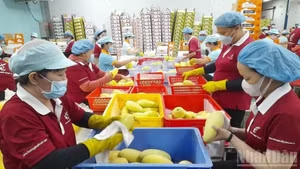
During the cinnamon harvest season, Viet Nam-India International Company needs around 40 billion VND to purchase raw materials and stockpile supplies for production until the next harvest. The harvest lasts just over a month, while payments for purchases must be made promptly so that growers can continue harvesting.
The company's director, Nguyen Thi Mai, said that once the raw materials are delivered to the factory, the business must pay growers within two to three days. As a result, its financing needs are heavily concentrated over a period of one to one and a half months.
This case illustrates how closely the timing of funding is linked to a business's production and operating cycle. Timely loan disbursement enables businesses to secure raw materials.
Conversely, delays can cause business opportunities to slip away, even when demand and viable plans for using the funds remain. For many businesses, particularly during harvest seasons, export periods and the year-end peak season, the time taken to process loan applications is also part of the cost of capital.
In the coffee sector, Le Dinh Tu, Director of Aeroco Coffee Co., Ltd. in Dak Lak, said the company is involved in production, processing, exports, and farm-based visitor experiences, yet access to credit remains an obstacle.
With resources having to be allocated to factory buildings, machinery, wages, and employees' insurance, the business has at times had to sell assets to keep operating. When it subsequently needs capital, its remaining assets may no longer meet collateral requirements, leaving it to find ways to finance its operations on its own.
Meanwhile, the banking system is stepping up funding for the SME sector.
According to Nguyen Xuan Bac, Deputy Head of the Credit Department at the State Bank of Viet Nam, total outstanding credit across the banking system reached 20.75 quadrillion VND at the end of September 2026, marking an increase of nearly 11.6% from the end of 2025 and 16.69% year on year.
For small and medium-sized enterprises alone, more than 100 credit institutions currently have outstanding loans to this group. Outstanding credit totalled over 4.1 quadrillion VND, up 12.4% from the end of 2025 and accounting for around 20% of the economy's total outstanding credit.
Notably, a credit programme launched in August 2026 targeting economic growth drivers and small and medium-sized enterprises has attracted participation registrations from 19 commercial banks, with a total funding scale of around 407 trillion VND.
Loans under the programme carry interest rates at least 1% per year lower than the lending bank's average rate for loans of the same tenor. However, an increase in available funding does not necessarily translate into a corresponding expansion in access to credit.
A report by FiinGroup recorded loan access rates of 8.8% among micro-enterprises and 30.9% among small and medium-sized enterprises. Across the SME sector, including micro-enterprises, the rate stood at 20.5%.
These figures point to a substantial gap between the credit available and businesses' ability to meet lending requirements.
Nguyen Thi Lan Huong, a member of the Presidium of the Central Committee of the Viet Nam Young Entrepreneurs Association, said that credit had consistently been one of the foremost concerns raised during 27 dialogue sessions with young businesses nationwide since the beginning of the year. Beyond advertised interest rates, businesses also face costs associated with insurance, asset valuation, completing documentation, and interest rate adjustment margins.
On the banking side, Bac said that compliance with risk management standards required complete and reliable information on how loans would be used and borrowers' repayment capacity.
Meanwhile, data on small and medium-sized enterprises remain incomplete and fragmented, with information from tax authorities, customs, social insurance agencies, and other sources not yet fully integrated. Some businesses have financial statements that lack transparency, with discrepancies between internal management figures and tax reports.
This shows that removing the obstacles requires action from both sides. Banks need a stronger basis for identifying customers capable of repaying loans, while businesses must demonstrate their own commercial viability more clearly.
If interest rates are reduced but barriers relating to information, collateral, and procedures remain, then preferential funding will struggle to reach businesses with viable plans that do not meet traditional lending assessment criteria.
Expanding credit through data
According to Pham Nhu Anh, chief executive officer of Military Commercial Joint Stock Bank (MB), interest rate cuts offer only a temporary solution and do not address the fundamental barriers to SMEs access to capital.
Many businesses have production capacity, orders and stable markets for their products, yet still struggle to obtain loans under lending approaches that rely primarily on collateral, financial statements, and independent credit ratings.
MB is therefore moving towards a multi-tier supply chain financing platform designed to channel capital to businesses at deeper levels of the supply chain. Other banks are also undergoing a similar shift.
Pham Toan Vuong, Chief Executive Officer of the Viet Nam Bank for Agriculture and Rural Development (Agribank), said the bank was moving decisively towards assessments based on cash flow, market outlets and the effectiveness of business plans, while standardising procedures, increasing electronic disbursements, and making greater use of data.
At the Joint Stock Commercial Bank for Foreign Trade of Viet Nam (Vietcombank), Deputy General Director Bach Thanh Long also advised businesses to improve their accounting systems, ensure cash flow transparency, and concentrate their revenue and payments through banks to generate data for credit assessments.
According to Dr. To Hoai Nam, Standing Vice Chairman and Secretary-General of the Viet Nam Association of Small and Medium Enterprises, banks cannot be expected to lower credit standards and shoulder the risk of bad debts. However, assessment methods can be changed to improve businesses' access to capital.
Account transaction records, electronic invoices, actual contracts, payment histories, and intellectual property rights should be used to provide additional evidence for credit assessments. When businesses' commercial viability is more fully reflected, they have a better chance of reducing their reliance on collateral.
Alongside improvements to lending assessments, risk-sharing mechanisms must also be made effective in practice.
Do Van Ve, Chairman of the Hung Yen Provincial Business Association, proposed improving the effectiveness of the Credit Guarantee Fund for SME, the SME Development Fund and other support instruments.
According to Ve, appropriate risk-sharing mechanisms, combined with banks adopting new assessment methods and businesses improving transparency, could broaden access to capital while maintaining credit safety. Alongside measures taken by banks, the institutional framework also needs further improvement.
The Ministry of Finance is currently drafting amendments to the Law on Support for Small and Medium-sized Enterprises, including renaming it the Law on the Development of Small and Medium-sized Enterprises, with a simultaneous focus on both the supply of and demand for capital.
On the one hand, the proposed approach seeks to encourage the development of credit sources, capital markets, and funding methods suited to businesses' revenues, cash flows, and business plans.
On the other, it aims to help businesses standardise financial information, strengthen their capabilities, expand their markets, and participate in value chains.
A proposal by Nguyen Van Than, Chairman of the Viet Nam Association of Small and Medium Enterprises, to study a pilot scheme for a dedicated digital bank serving small and medium-sized enterprises and household businesses also aims to diversify sources of funding.
Ultimately, for these solutions to be effective, economic experts stress that small and medium-sized enterprises must proactively improve their management, maintain transparent accounts, and develop viable business plans.
When policymakers, banks, and businesses work together to remove each bottleneck, capital can be translated into productive capacity, jobs, and added value, making a tangible contribution to economic growth.