Reducing inspections and strengthening support to prevent errors
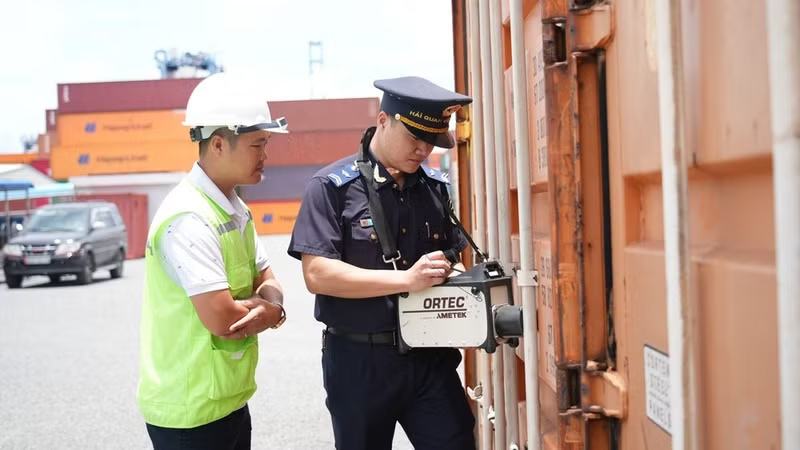
Customs clearance waiting times, warehousing and storage costs, and labour costs associated with physical inspections all affect the operations of import-export businesses. Therefore, reducing inspections of businesses that comply well with the law is a practical way to facilitate their operations, allowing them to benefit from their own efforts to maintain compliance.
According to Quach Dang Hoa, Head of the Risk Management Department under the Viet Nam Customs Department, after many years of implementation, risk management is entering a new stage of development, becoming more closely integrated with business compliance management and the application of digital data. This approach serves two objectives simultaneously: targeting high-risk entities for customs controls and providing greater facilitation for businesses.
Previously, blanket inspections or inspections based on customs officers' subjective judgement could impose time and cost burdens even on businesses with good compliance records. The regulatory authorities’ inspection resources were also spread thin, despite the need to focus on entities requiring closer scrutiny.
Viet Nam has gradually shifted towards risk-based management in accordance with recommendations from the World Customs Organization. In particular, the 2014 Law on Customs established this approach for customs management before, during and after clearance. The selection of entities for inspection and supervision has increasingly been based on systematic assessments, with businesses’ levels of legal compliance serving as an important criterion.
Quach Dang Hoa explained that risk management and compliance management are closely related but serve different assessment purposes. Risk management helps identify risks associated with individual consignments, while compliance management examines businesses’ entire operating history to determine its level of reliability and the appropriate degree of intervention. The two approaches complement each other through a shared data platform.
Customs authorities therefore need to consider businesses’ compliance histories, behaviour and compliance trends, alongside information about individual consignments. This approach provides a basis for distinguishing businesses that consistently maintain good compliance from high-risk entities, allowing proportionate management measures to be applied.
According to Hoa, reviewing and adjusting customs declaration classification criteria to focus on genuinely high-risk entities has helped increase the proportion of declarations assigned to the green channel while reducing those assigned to the yellow and red channels. These results have shortened customs clearance times and reduced business costs while maintaining risk controls and safeguarding economic security.
Alongside adjustments to inspection practices, helping businesses proactively prevent errors is another important priority. A programme to encourage and support voluntary compliance with customs legislation has attracted 397 participating businesses. Of these, 355 have maintained their compliance levels, while 13 have had their compliance ratings upgraded.
In the first six months of 2026, customs authorities received and resolved 145 issues raised by participating businesses. Through this support, businesses have been able to identify risks and prevent errors during customs procedures, rather than waiting for regulatory authorities to detect and address violations.
This is also an important consideration in expanding compliance management. Assessing and classifying businesses must go hand in hand with helping them fulfil their obligations correctly. By identifying shortcomings in legal compliance, customs authorities can select appropriate support and management measures for each group of businesses.
According to Hoa, the ultimate objective goes beyond changes in customs declaration channel rates or clearance times. Businesses that invest in management systems and internal controls and maintain good compliance records should receive corresponding benefits. In this way, legal compliance can gradually become a genuine advantage in business operations.
Assessing businesses through continuously updated data
An important institutional development is Law No. 11/2026/QH16, amending and supplementing several articles of the Law on Customs, which was passed by the National Assembly on August 23, 2026, and will take effect on March 1, 2027. The amendments to Article 17 on risk management and the addition of Article 17a on compliance management provide a legal foundation for the new management approach.
According to Hoa, a notable feature is that compliance management is now regulated directly and independently at the legislative level. Customs inspection and supervision will be conducted through a combination of risk management and compliance management, establishing a clearer link between businesses’ records of legal compliance and the management methods applied by customs authorities.
Under the new regulations, customs declarants who comply with the law may be considered for priority treatment in completing customs procedures, as well as exemptions from or reductions in customs inspections, supervision and post-clearance audits. These provisions provide a basis for putting into practice the principle that the better a business complies with the law, the greater the facilitation it receives.
Eligibility for such facilitation will depend on compliance assessment results and specific implementation mechanisms. Therefore, alongside the new legal framework, the customs sector is drafting decrees and circulars to replace Decree No. 08/2015/ND-CP and Circular No. 81/2019/TT-BTC, translating these principles into operational mechanisms.
To ensure coordinated implementation, the customs sector is developing a compliance management system comprising several interconnected stages. The first is to identify the obligations businesses must fulfil, followed by measuring and assessing their compliance status, behaviour, trends and shortcomings. Monitoring activities will help detect changes promptly so that management measures can be adjusted accordingly.
Assessment results will provide the basis for classifying businesses according to their behaviour, implementing voluntary compliance promotion programmes and applying measures proportionate to each compliance level. Under this approach, business assessments will become an ongoing process, updated in line with actual developments in import-export activities.
All assessment results will be integrated into business compliance profiles, providing a common basis for both risk management and compliance management. These profiles will function as a central data repository, continuously updated to enable customs authorities to monitor each business’s compliance history over time.
Hoa said digital transformation is a central pillar throughout this process. The customs sector aims to strengthen data integration and standardisation, improve risk analysis and early warning capabilities, and gradually automate profile management, compliance assessments and the identification of priority areas for customs controls.
As these processes become interconnected, business assessments will gradually shift from manual processing to continuous data-driven evaluation. This approach will also reduce the need for businesses to resubmit information already held by state agencies, in line with the spirit of Resolution No. 57-NQ/TW on breakthroughs in science, technology, innovation and national digital transformation.
Data therefore play a direct role in management decisions. Integrated, standardised and updated information provides customs authorities with a basis for assessing businesses’ compliance levels, identifying changes and determining priorities for customs controls. A shared assessment framework also supports consistent implementation of risk management and compliance management.
According to Hoa, integrating these two approaches is intended to improve the business environment, reduce compliance costs and provide support for businesses, in line with the spirit of Resolution No. 68-NQ/TW on private sector development. When efforts to strengthen corporate governance and comply with the law are recognised through tangible benefits, businesses gain further incentives to maintain compliance.
For customs authorities, concentrating resources on high-risk entities will help improve the effectiveness of controls. For businesses, the benefits should be reflected in appropriate levels of intervention and reductions in the time and costs involved in completing customs procedures. This is how regulatory requirements and trade facilitation objectives can be achieved together throughout the customs reform process.