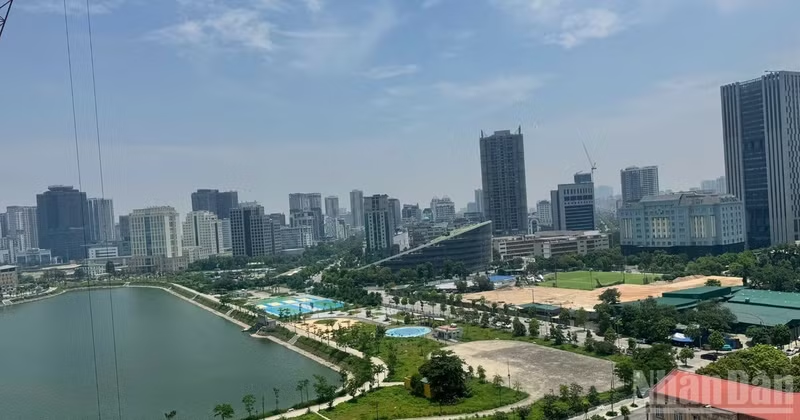
As the market gradually shifts from developing properties for sale towards long-term asset ownership and operation, choosing the right market entry strategy is becoming an increasingly important part of investment planning.
From choosing asset classes to selecting market entry strategies
According to Savills, the Living Sector market in Asia-Pacific does not follow a single model. Investment opportunities vary considerably across countries, asset types and, particularly, the ways in which investors enter the market.
Five main approaches have emerged: repositioning distressed assets, repurposing obsolete properties, developing new projects, investing in operating platforms through mergers and acquisitions (M&A) or growth capital, and directly acquiring stabilised assets.
This reflects an important shift in how investors approach the sector. Rather than simply asking, "What type of property should we invest in?", they must also consider, "How should we enter the market?" Operational capabilities, demand characteristics, regulatory frameworks, development costs and the potential to generate long-term cash flow can all influence the effectiveness of each strategy.
Viet Nam: An emerging demand base
In Viet Nam, the Living Sector remains at a relatively early stage of development compared with some of the region's more mature markets. However, several related segments are already demonstrating clear rental demand, particularly in Ho Chi Minh City and Ha Noi.
In Ho Chi Minh City, the serviced apartment segment recorded approximately 7,000 units in the second quarter of 2026, with an occupancy rate of 84% and average rents of nearly 560,000 VND per square metre per month. Notably, supply declined as several smaller Grade C projects exited the market or temporarily closed for renovation, while overall performance improved on the back of demand for well-managed properties.
In Ha Noi, the serviced apartment market also maintained occupancy above 80% in the second quarter of 2026, with more than 6,500 units across 67 projects. Demand was supported by foreign direct investment (FDI) inflows and expatriate tenants. The continued expansion of industrial parks, industrial clusters and high-tech zones is also expected to further strengthen accommodation demand.
These developments indicate that demand for professionally managed and operated residential properties already exists in certain market segments. However, the market remains largely composed of individual properties, while Living Sector models developed and operated as long-term investment assets are still relatively new.
Across the broader residential market, affordability is also becoming an increasingly important consideration. In Ho Chi Minh City, average primary residential prices exceeded 90 million VND per square metre in 2026, while 80% of supply was priced above 120 million VND per square metre. This could create favourable conditions for professionally managed rental housing models to develop over the longer term, particularly if urban populations, workforce mobility and demand for flexible accommodation continue to increase.
Neil MacGregor, Managing Director of Savills Viet Nam, said: "In Viet Nam, we are seeing growing demand for professionally managed residential products, particularly in cities with strong economic activity and international capital flows."
According to MacGregor, the market remains fragmented, but this also presents opportunities for models capable of combining long-term capital with operational expertise. When assessing a Living Sector investment opportunity, investors need to consider not only the value of the property itself but also how it is managed, how occupancy is maintained and how it generates cash flow over the long term.
Three approaches for the Vietnamese market
One approach gaining traction across Asia-Pacific is the conversion of properties that no longer meet their original purposes into Living Sector models. Hotels, office buildings and other property types could be considered for conversion into co-living spaces (modern shared-living arrangements designed for groups of young people with similar interests or occupations), student accommodation or long-stay residential facilities, depending on their location, physical structure and ability to meet regulatory requirements.
In Ha Noi and Ho Chi Minh City, this approach offers potential for repurposing underperforming properties rather than always starting with new developments.
However, its effectiveness will depend heavily on renovation costs, the feasibility of changing a property's use and the operating model adopted after conversion.
Experience across Asia-Pacific also shows that investment capital is increasingly flowing towards operating platforms rather than focusing solely on individual properties. An operator capable of managing a portfolio, applying technology, controlling costs and maintaining a consistent tenant experience can generate value on a larger scale than managing properties independently.
This could be a particularly promising approach in Viet Nam, where the rental market remains fragmented. The combination of long-term capital with local operational expertise could help establish larger, more consistent property portfolios.
Another approach is the build-to-rent model, in which properties are designed and developed from the outset specifically for rental purposes and long-term ownership. Unlike the build-to-sell model, build-to-rent focuses on the entire asset lifecycle, from location, product design, amenities and unit mix to occupancy rates, operating costs and the ability to maintain sustainable cash flow.
In Viet Nam, this model could be considered in areas with stable rental demand, particularly as urban centres continue to expand along transport corridors and around emerging economic hubs.
The development of the Living Sector does not necessarily replace traditional residential property models. Rather, it broadens the perspective on housing as an asset class that can be owned, operated and used to generate long-term income.
In Viet Nam, signals from the serviced apartment market indicate that demand for professionally managed residential properties already exists, while housing affordability challenges continue to drive the need for a wider range of accommodation options.
Against this backdrop, opportunities in the Living Sector will lie not only in expanding supply but also in identifying suitable asset types, appropriate market entry strategies and operating models tailored to individual markets. This could provide the foundation for the income-generating residential property segment to gradually establish a stronger presence in Viet Nam.