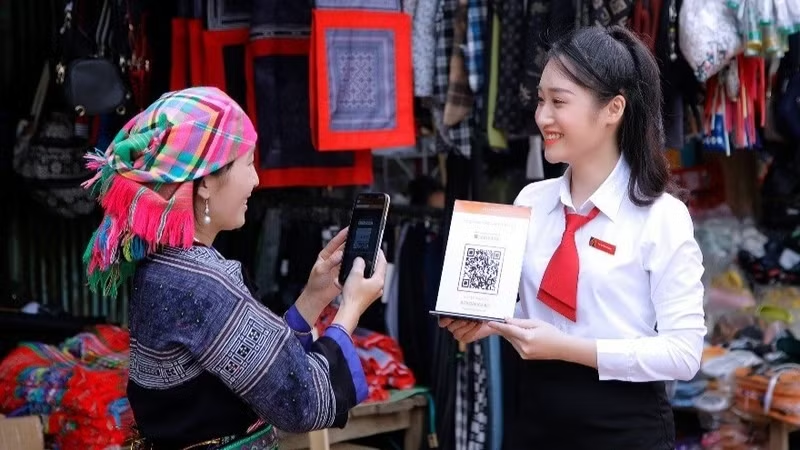
Positive results in cashless payments have laid an important foundation for promoting financial inclusion. However, further progress in the coming period will require continued efforts to narrow gaps in access to financial services among different population groups and geographical areas. Nguyen Phi Lan, Director of the State Bank of Viet Nam’s Forecasting and Statistics Department, shared his views on the issue.
Q: Cashless payments have grown rapidly in recent years. What are the major gaps that still need to be addressed to make cashless payments a genuine driver of financial inclusion?
A: According to our statistics, cashless payment transactions grew by an average of more than 60% annually during 2021–2025. This is a significant achievement, reflecting the strong growth of cashless payments in recent years.
On May 25, 2026, the Prime Minister issued Decision No. 928/QD-TTg approving the National Financial Inclusion Strategy for 2026–2030. In advising on the development of the strategy, the State Bank of Viet Nam assessed the results of the previous period and identified the difficulties and challenges that need to be addressed in the years ahead.
One important issue is the continued improvement of the legal framework, with greater attention to protecting consumers, particularly users of digital financial services and vulnerable groups in society.
The use of financial services remains more concentrated in major cities and urban areas. Meanwhile, people in remote and mountainous areas, as well as groups with specific needs, still face gaps in their ability to access and use financial products and services. The legal framework therefore needs to take their particular circumstances into account.
Another issue is financial infrastructure, especially digital financial infrastructure. Significant differences remain between urban areas and remote regions. The challenge is to expand and integrate infrastructure while ensuring that it meets the conditions of each locality.
Financial service providers’ capacity to supply products is also a concern. In cities, people can pay conveniently by mobile phone or QR code. However, cash remains widely used in many remote areas. This highlights the need to develop more suitable products and establish distribution networks that can bring services closer to local communities.
Cash-dependent habits also need to change. This is not merely a technological issue but one that involves the behaviour of both buyers and sellers. Financial education, communication and efforts to change how people use financial services therefore remain important.
Finally, stakeholder participation is essential. Promoting financial inclusion and cashless payments is not solely the responsibility of the banking sector; it requires coordination among ministries, sectors, service providers and international organisations.
Q: What are the biggest challenges to narrowing gaps in access to financial services across population groups and geographical areas? Are they infrastructure, costs, technology or cash-dependent habits?
A: In my view, technology will remain a major challenge, both today and over the next five to ten years. It is an important tool for narrowing gaps in access to financial services, but a key issue is the ability of service providers to integrate their systems with those of organisations adopting and using the technology.
Our field surveys have found that information technology adoption remains limited in some schools and hospitals. This makes it difficult for service providers to deliver their products, or means that their products are not fully suited to users’ needs, thereby increasing service delivery costs.
When costs become too high, organisations that need these services may also be reluctant to adopt them. This is one factor that could hinder the expansion of cashless payments and make it harder to narrow gaps between regions, particularly in remote and disadvantaged areas.
The challenge, therefore, is not simply to develop technology, but also to improve system integration, ensure that solutions are fit for purpose and keep costs under control. Technology should make services more convenient and accessible, rather than create additional barriers for users.
Security is equally important. As financial services become increasingly digitalised, consumer protection must go hand in hand with ensuring security and safety throughout the use of these services. This requires the involvement and coordination of multiple ministries and sectors.
Q: Looking ahead, which solutions should be prioritised to achieve the objectives of the National Financial Inclusion Strategy and promote digital payments?
A: One key priority is to expand access to financial services for a wider range of groups. Financial inclusion should serve not only urban residents but also people in rural areas, households, small and medium-sized enterprises, women, young people, vulnerable groups and startups.
First, we need to develop a diverse range of financial products tailored to the characteristics and needs of different groups. To enable people and businesses to access financial services, it is essential to offer products that meet their needs.
To diversify these products, financial service providers, including banks and technology companies, need to make greater use of science and technology to deliver solutions that are more efficient, faster, more convenient and less costly, making them easier for people and businesses to access and use.
The second priority is to further promote the application of science and technology in conjunction with the modernisation of the banking sector. Technology must help deliver financial products to consumers more quickly and conveniently while ensuring safety and security.
The third is to improve infrastructure. This is crucial because infrastructure directly affects security, safety, data protection and users’ trust. If users do not feel safe, they may choose not to use the services, regardless of how many products are available.
Trust is therefore fundamental. It must be built on reliable technology and robust security, safety and data protection systems. These issues are also emphasised in programmes and schemes for financial inclusion and banking modernisation.
Finally, financial education is essential. It helps people not only learn how to use financial products but also protect themselves. Even with strong security and data protection systems, safeguarding users remains difficult if they are not alert to scams and fraud.
Improving people’s financial literacy, their ability to use financial services and their capacity to protect themselves should therefore be regarded as a key component of efforts to promote financial inclusion in the coming period.
Thank you very much!